How to Document Home Damage for an Insurance Claim
Key takeaways
- Photograph and video everything before you clean up. Maryland and DC regulators both say this plainly, and it is the step people skip.
- The burden of proving the loss is yours. Virginia regulators put that in writing in their consumer guide.
- Make emergency repairs to stop further damage, keep the receipts, and hold off on permanent repairs until the adjuster has seen it.
- A typical policy gives you 60 days to return a sworn proof of loss after the insurer asks for it, not 60 days from the date of damage.
- Maryland and Virginia set deadlines for the insurer. DC requires only that it act reasonably promptly, which makes your own written record matter more, not less.
The pipe lets go at two in the morning. By the time you have the water off, there is an inch across the basement floor and your first instinct, a completely human one, is to start moving things and pulling up carpet.
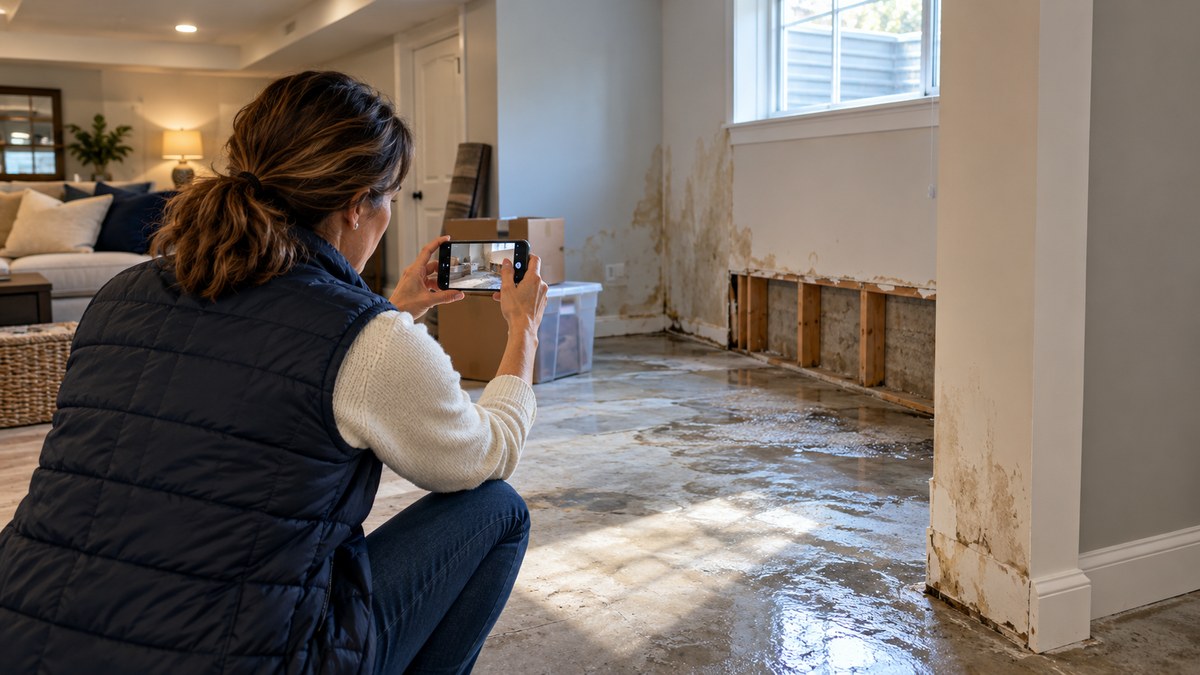
Stop for ten minutes first. Those ten minutes are worth more to your claim than anything else you will do that week.
Document before you clean up
This is the one point every insurance regulator in our area agrees on, and it is the one homeowners most often get wrong.
The DC Department of Insurance, Securities and Banking tells consumers to take photographs or video of the damage before clean up and repairs. The Maryland Insurance Administration goes further and says that before you remove damaged property from the premises, you should be sure an adjuster or your agent has seen it. Maryland flags a specific reason that matters after a storm: if state or local officials begin debris removal on your property, your evidence leaves with the debris.
Practically, that means:
- Shoot a wide establishing shot of each affected room first, then close ups of each damaged item. The wide shot proves where something was. The close up proves how bad it is.
- Photograph the cause as well as the result. Most people take twenty pictures of the ruined floor and none of the failed supply line, the missing shingles or the tree.
- Keep the original files rather than screenshots or copies sent through a messaging app, so the timestamps stay intact.
- Photograph serial numbers, model plates and brand labels on appliances and electronics.
- Take a before and after pair around any mitigation work, so that drying out the basement does not later look like you destroyed the proof.
- Keep damaged material. A cut section of wet drywall or a hail struck shingle, bagged and labeled in the garage, is evidence.
Where wind driven rain and rising water hit the same house in the same storm, coverage can turn on the sequence of events and the height of the water line. Only photographs taken at the time can establish either one.
What your policy actually requires of you
Most homeowners have never read the duties after loss section, which is a shame, because it is short and it is the part that decides how smoothly a claim goes. On a standard form the named duties are roughly these:
- Give prompt notice to the insurer or the agent.
- Notify the police in case of theft.
- Protect the property from further damage, make reasonable and necessary repairs to do so, and keep an accurate record of what those repairs cost.
- Cooperate with the investigation.
- Prepare an inventory of damaged personal property showing quantity, description, actual cash value and amount of loss, and attach the bills and receipts that justify the figures.
- Show the damaged property, provide records on request, and submit to an examination under oath if asked.
- Send a signed, sworn proof of loss within 60 days after the insurer requests it.
That last one is worth slowing down on, because it is the single most commonly misstated fact about home claims. On a typical homeowners form, the 60 day clock starts when the insurer asks for the proof of loss, not on the day the damage happened. Virginia is a partial exception, because the standard fire policy language written into Virginia law runs its own 60 days from the loss itself. Either way, the document that controls is your policy, so read the request letter carefully and diarize the date.
One more piece of that list deserves emphasis. Failing to protect the property from further damage is not merely a broken promise. On most forms, neglecting to use all reasonable means to save and preserve the property after a loss is an actual exclusion. Tarp the roof, board the window, get the water extracted.
Emergency repairs yes, permanent repairs no
Maryland puts the line clearly. Before the adjuster inspects, make only the repairs necessary to prevent further damage, which includes covering roofs, walls or windows with plywood, canvas or other waterproof material. Do not have permanent repairs made without consulting the insurance company first, and if approval is given, get it in writing. Unauthorized repairs may not be reimbursed. DC says the same thing in fewer words.
Keep the emergency services invoice, the water extraction, the board up, the tarp, separate from the reconstruction estimate. When those costs are mixed into one bill, the mitigation piece gets harder to recover cleanly.
The burden of proof is yours
The Virginia Bureau of Insurance says it about as plainly as a regulator ever says anything. Asked whether an insurer can require proof that you owned what you are claiming, the state consumer guide answers yes, and adds that the ultimate responsibility of proving the loss is yours.
That single sentence is the argument for doing a home inventory now, on an ordinary Saturday, rather than trying to reconstruct one from memory while you are living in a hotel. The National Association of Insurance Commissioners publishes a free Home Inventory app for iOS and Android that lets you photograph items room by room, scan barcodes and export the list. It costs nothing and an afternoon with it is the best insurance related chore most homeowners never do.
Whatever tool you use, keep a copy somewhere other than the house. A perfect inventory that burns with the building has not helped anyone.
What the insurer owes you, and how the three jurisdictions differ
This is where Maryland, Virginia and DC genuinely diverge, and it is useful to know which set of rules you are under.
Maryland
Under Maryland regulation, an insurer is expected to acknowledge a claim within 15 working days and to affirm or deny coverage within 15 working days of receiving properly completed proofs of loss. If the investigation is not finished within 45 days of notification, the insurer must tell you in writing why more time is needed, and repeat that every 45 days until it affirms or denies. A denial has to identify the provision, condition or exclusion it rests on.
Virginia
Virginia runs on similar timing in calendar rather than working days. An insurer must acknowledge within 15 calendar days, advise you of acceptance or denial within 15 calendar days of receiving a properly executed proof of loss, and send a written explanation every 45 days while an investigation continues. Denials must be in writing with specific reference to the policy language. Virginia also has a provision worth knowing: when an insurer prepares a repair estimate, it is required to give you a copy. Ask for it.
The District of Columbia
DC sets no fixed number of days. Its statute requires insurers to acknowledge and act reasonably promptly, to affirm or deny within a reasonable time, and to give a reasonable and accurate explanation for a denial. That flexibility cuts both ways. In DC, your own dated record of every call and email is doing work that a statutory deadline does elsewhere.
DC regulators recommend keeping a diary of conversations with your insurance company and your agent. Do it everywhere. Date, time, name, direct number, what was said.
Two Maryland specifics worth checking before the storm, not after
Mismatched siding and roofing. If hail damages one side of the house, the insurer is generally responsible for repairing or replacing that side. Maryland has no matching statute. Whether you get help with the mismatch depends on whether your own policy contains a mismatch exclusion, and many do. Where a replacement cost policy has no such exclusion, an appearance allowance may be available if you can show the mismatch hurts the value of the home. Some carriers sell a mismatch endorsement. It is a good question to ask at renewal.
The hurricane deductible trigger. Maryland law ties a percentage hurricane deductible to a specific window. It applies only from the time the National Hurricane Center issues a hurricane warning for any part of the state until 24 hours after the last such warning ends, and it applies regardless of where in Maryland the home sits. Because the window is defined by time, the date and hour of the damage matters. Note it in your photographs and your log.
A short list to keep somewhere you can find it
- Photograph and video everything, cause and result, before any cleanup.
- Call it in and write down who you spoke with.
- Stop further damage, keep those receipts separate, and leave permanent repairs alone until the adjuster has been out.
- Build the inventory with quantity, description, age, original cost and replacement cost today.
- Be present for the inspection so nothing gets missed.
- Keep every piece of paper, and get any denial in writing.
We help homeowners across Gaithersburg, Rockville, Montgomery County and the wider DMV think through this before it happens, which is the only time it is easy to think about. If you are not sure what your own policy requires of you, send us the declarations page and we will read it with you.
Frequently Asked Questions
How long do I have to file a homeowners claim?
Your policy requires prompt notice rather than a fixed number of days, so call it in as soon as you reasonably can. The separate 60 day deadline people remember is for returning a signed, sworn proof of loss, and on most homeowners forms that clock starts when the insurer requests it, not on the date of the damage.
Should I clean up before the adjuster arrives?
Document first, then do only what is needed to stop the damage from getting worse. Maryland advises making sure an adjuster or agent has seen the damage before you remove damaged property, and both Maryland and DC advise against permanent repairs until the insurer has inspected.
Will my insurer pay for the tarp and the water extraction?
Generally yes. A standard form covers the reasonable cost of necessary measures taken to protect covered property from further damage, though that payment usually comes out of the applicable coverage limit rather than adding to it. Keep those invoices separate from the reconstruction estimate.
What should a home inventory actually include?
Maryland recommends a description and quantity, the purchase date or approximate age, the original cost, and an estimated replacement cost today. Photographs of serial numbers and model plates make the list far easier to support, and a copy should live somewhere other than the house.
How quickly does my insurance company have to respond?
In Maryland the standard is 15 working days to acknowledge and, once proofs of loss are in, 15 working days to affirm or deny, with written updates every 45 days during a longer investigation. Virginia uses 15 calendar days and the same 45 day update cycle. DC sets no fixed number and requires only that the insurer act reasonably promptly.
Related reading from Capitol Benefits
Ready when you are
Let's take a look at what you've got.
A real review of your current coverage. No deck, no pressure, and usually some money saved along the way.